

12 October 2026

Alexander Chieffalo
In this article
In this edition of Monday Market Minute, Alexander Chieffalo reviews the pullback in technology stocks, gold’s recovery and competing pressures on oil. US inflation and Australian employment are among the key releases to watch during the week commencing 12 October 2026.
Monday Market Minute
Monday Market Minute | Week commencing 12 October 2026.
Market overview
Tech set the tone last week. Reports that OpenAI’s annualised revenue was well below the figure investors had been working with knocked semiconductor stocks lower and pulled the Nasdaq 100 off its record, reopening the question of whether AI spending will pay for itself. That question reaches beyond tech, because AI investment has carried a large share of both US stock gains and economic growth this year.
The Fed did little to calm nerves. Minutes from September showed unanimous support for the hike but a split on whether it marked a one-off or the start of a cycle, and officials since have leaned towards more. Households are already uneasy, with confidence sliding even as they expect prices to keep rising. Markets price a hold this month and a December hike as the more likely path, which puts Wednesday’s inflation report at the centre of the week.
The Gulf is heating up again. The Houthis have seized territory near the Bab el-Mandeb, the southern entrance to the Red Sea, and their strikes on Riyadh’s airport have drawn a Saudi counteroffensive. That puts a second shipping chokepoint at risk alongside Hormuz, even as Washington pushes more fuel into the market through Russian diesel imports and a declared energy ceasefire between Russia and Ukraine.
Outside the US, France’s bond turmoil is weighing on the euro, with borrowing costs near quarter-century highs and a presidential election seven months away. China moved to defuse a trade fight with Europe ahead of Thursday’s EU summit, while RBA minutes, Australian jobs and two speeches from Bank of Canada Governor Macklem round out the week.
Week Ahead Calendar
Dates shown in UTC. Markets to watch are listed in parentheses.
Monday 12 October
- US bond market closed for Columbus Day (USDX)
Tuesday 13 October
Wednesday 14 October
- China CPI (HK50)
- ECB President Lagarde speeches (EUR/USD)
- BoC Governor Macklem speech (USD/CAD)
- US CPI (USDX, NDX100, XAU/USD, BTC/USD)
Thursday 15 October
- Australian employment (AUD/USD)
- US PPI and retail sales (USDX, NDX100)
- EU leaders meet on China trade (HK50, EUR/USD)
Friday 16 October
- BoC Governor Macklem speech (USD/CAD)

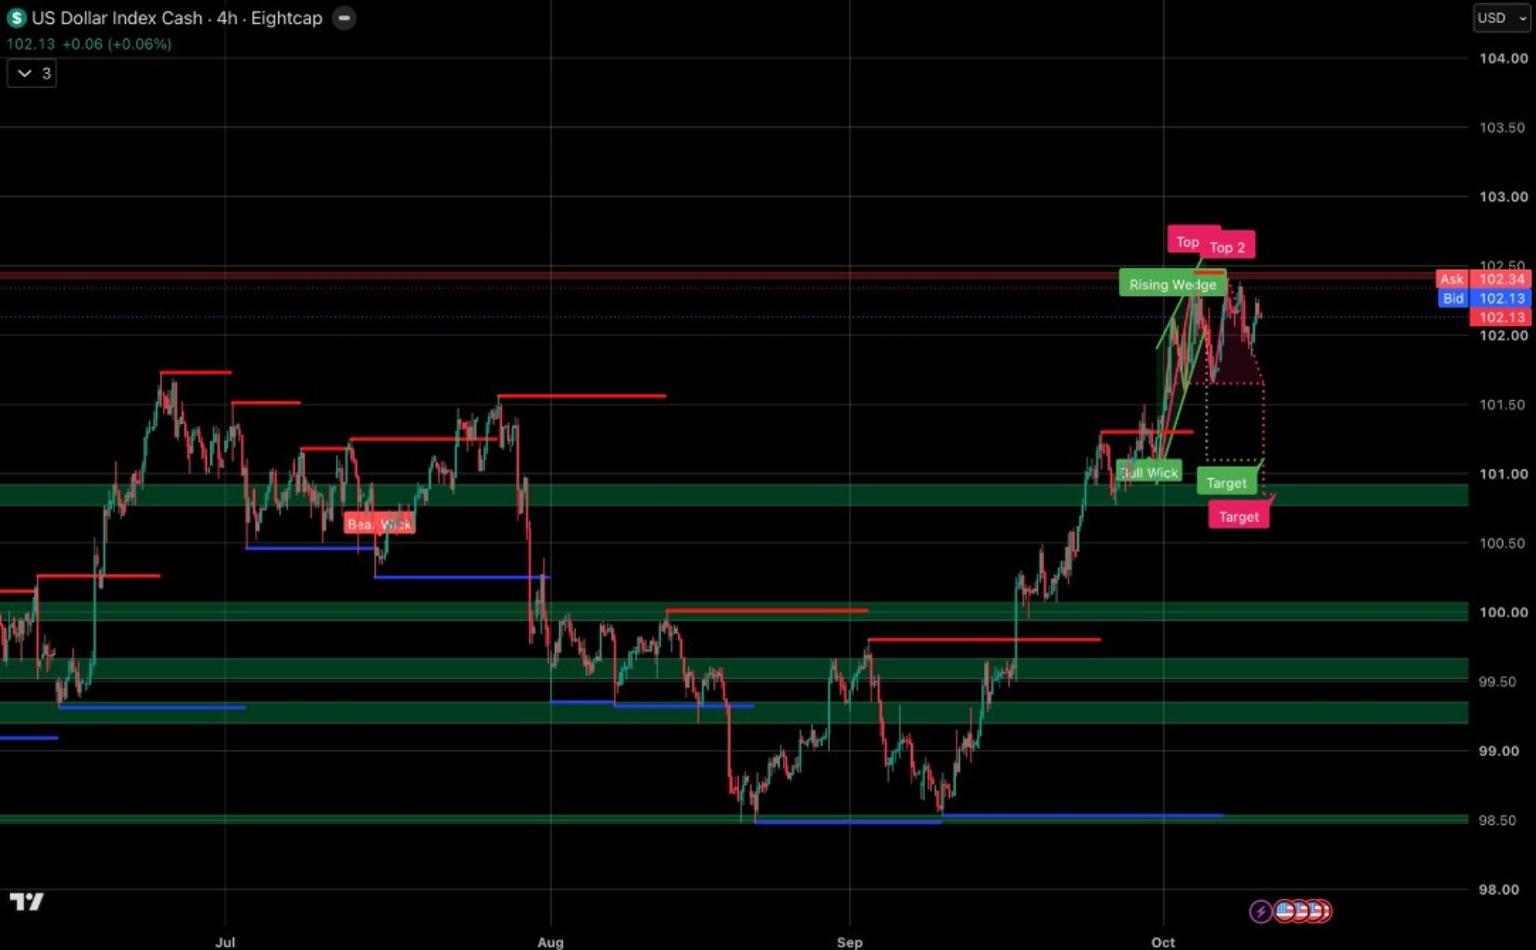
US Dollar Index (USDX)
The US Dollar Index trades at 102.13, just below its early October high near 102.40. Fed Governor Christopher Waller backs further hikes, though not necessarily at consecutive meetings, and St. Louis Fed President Alberto Musalem says a strong labour market means inflation has to come first.
Wednesday’s CPI is expected to show headline inflation rising to 3.7% from 3.4%, with producer prices and retail sales following on Thursday. Economists in the latest WSJ survey now expect the 10 year yield to end the year at 5.1%, up from 4.4% in July, which keeps the dollar’s rate support in place.
Price Levels
- Support: 101.64 → 101.30 → 100.78
- Resistance: 102.45 → 103.00 → 103.50
Technical View: A rising wedge from late September has formed a potential double top near 102.40, with measured targets between 100.70 and 100.85. The 101.00 zone, where a bull wick marked the last dip, is the key support.
Outlook: Bullish bias. Euro weakness and yields economists expect to stay high keep the dollar supported, though the double top means a soft CPI could bring a sharper pullback.
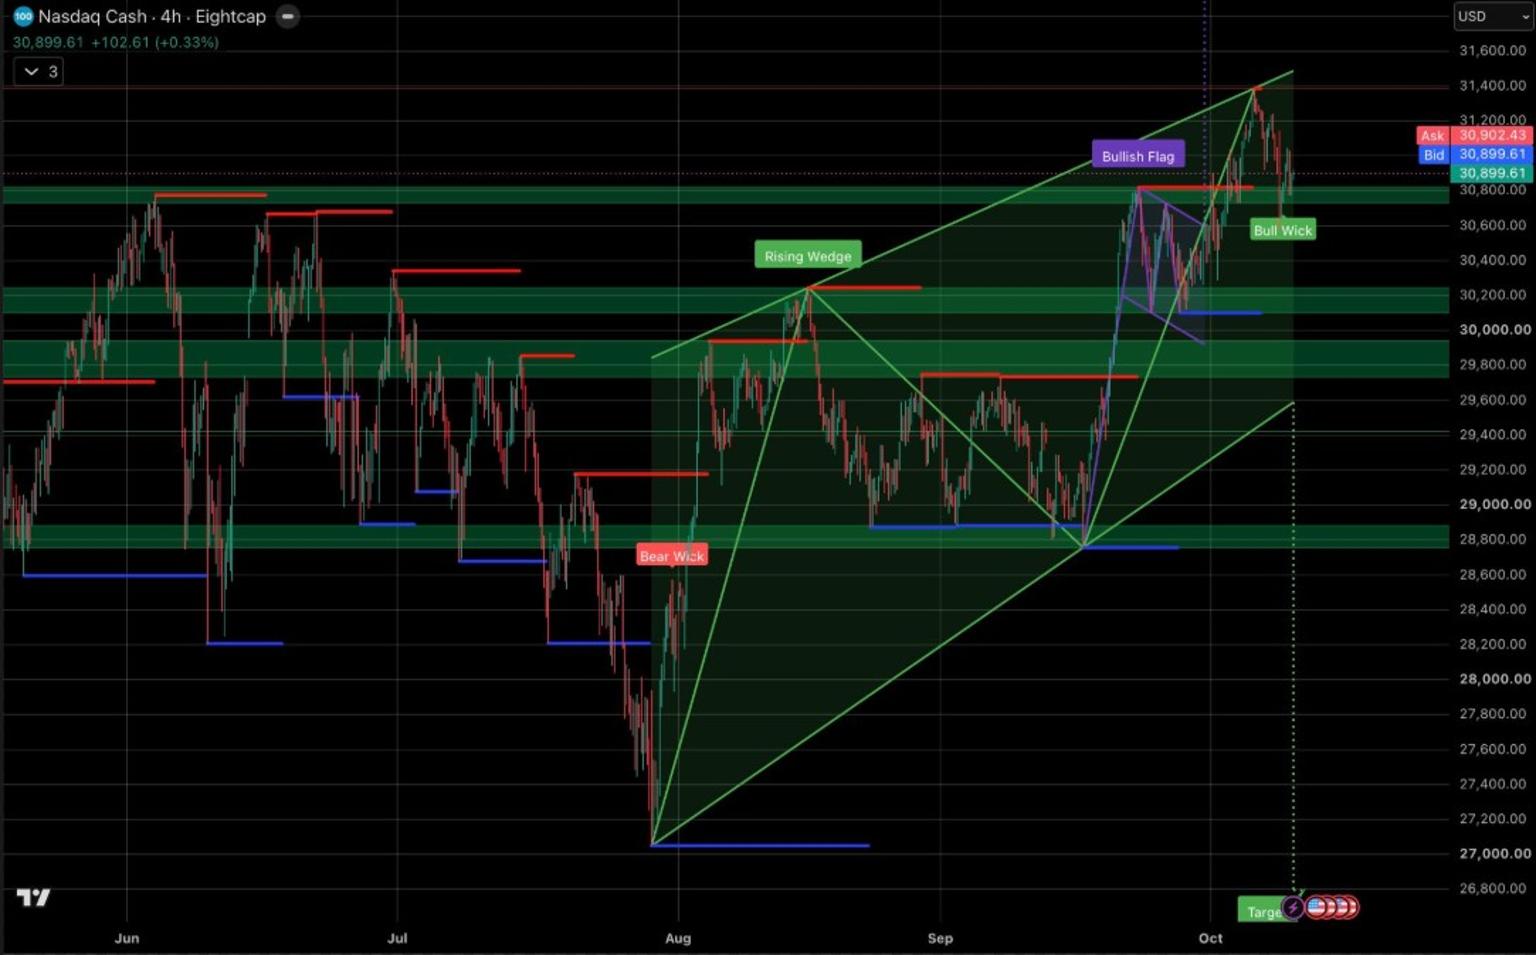
Nasdaq 100 (NDX100)
The Nasdaq 100 trades at 30,899 after reports put OpenAI's annualised revenue at about $50bn, around $20bn below figures previously circulated. Chipmakers took the brunt on Thursday, with Nvidia down about 3% and Broadcom more than 4%.
Part of the gap reflects how sales through cloud partners are counted, but the reaction shows how much of the index's run rests on AI spending paying off. Bank earnings this week offer a read from outside tech, with financing for hedge funds now one of Wall Street's fastest-growing businesses.
Price Levels
- Support: 30,730 → 30,250 → 29,940
- Resistance: 31,035 → 31,250 → 31,400
Technical View: Last week's flag breakout ran to about 31,400 at the upper line of the rising wedge from the late July low, then reversed. A bull wick near 30,700 is holding for now.
Outlook: Consolidating. The AI revenue scare knocked the index off its record, but the uptrend is intact and the market needs earnings or spending data to decide whether Thursday was a wobble or a turn.
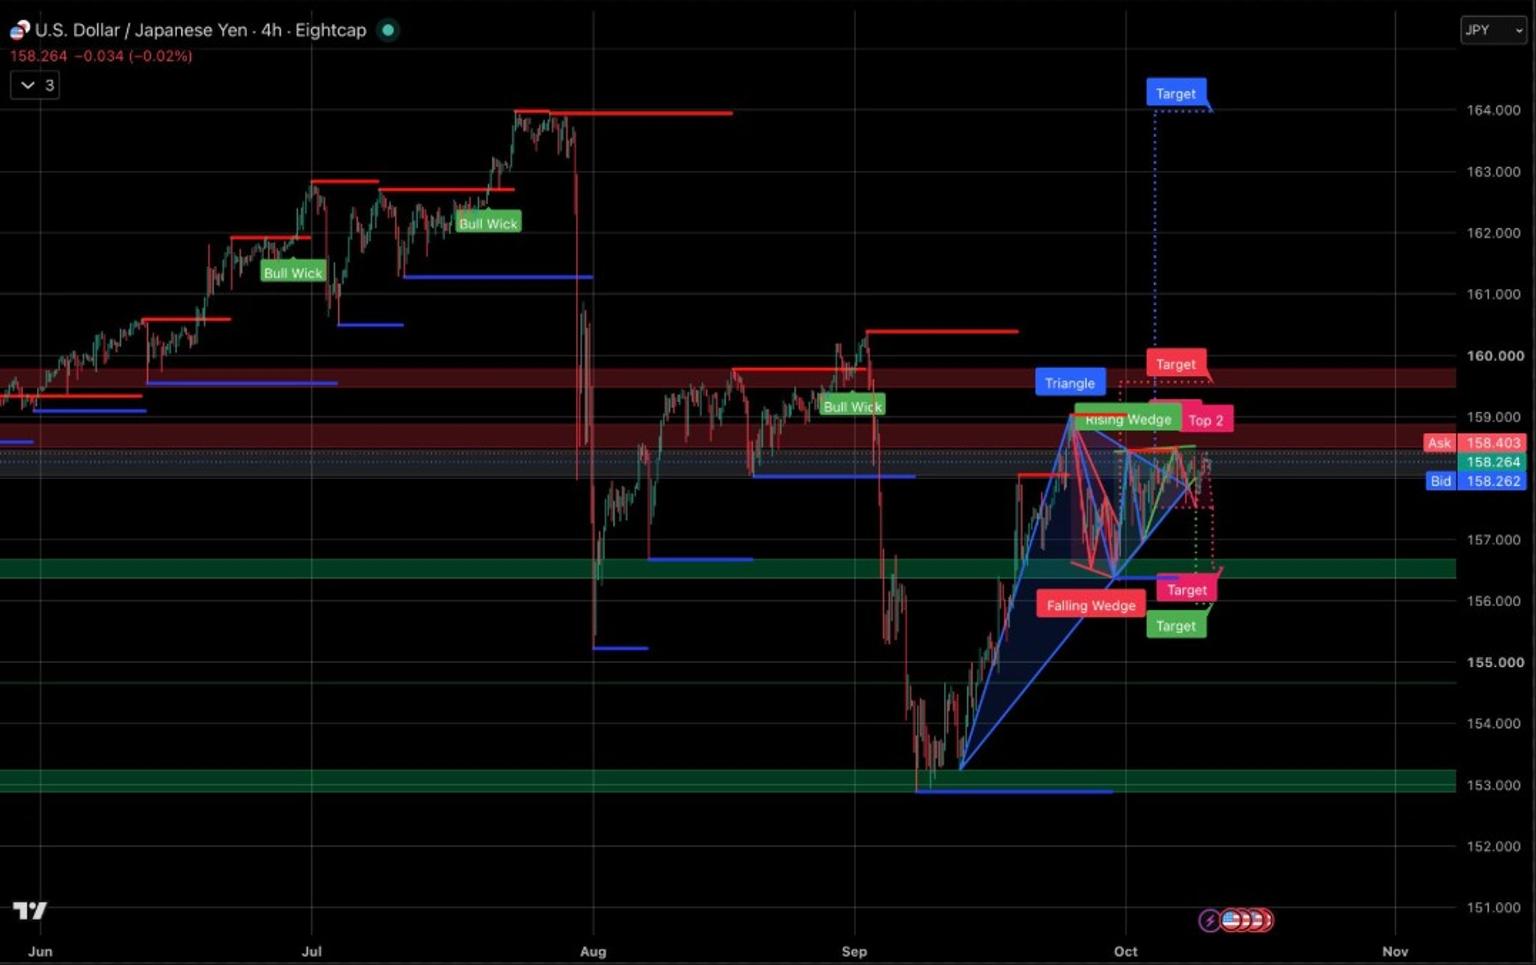
Japanese Yen (USD/JPY)
USD/JPY trades at 158.26, stuck in a tight range beneath the 200-day moving average near 158.54. Japan's domestic picture is soft, with household spending down 3.1% from a year earlier in August, its eighth straight decline, but new BoJ board member Ayano Sato has backed gradual tightening ahead of the 29 to 30 October meeting.
With no Japanese data of note this week, US CPI is the catalyst. A hot print widens the rate gap and pushes the pair toward the 159 to 160 zone where Tokyo has intervened before, while a soft one gives the yen room to recover.
Price Levels
- Support: 157.60 → 156.40 → 155.34
- Resistance: 158.50 → 159.03 → 160.40
Technical View: The September triangle has narrowed into a potential double top near 158.50, with a measured target around 156.20. A break above 159.03 would void it and open the triangle's upside target near 159.60.
Outlook: Rangebound. Weak domestic demand and a more hawkish BoJ board pull in opposite directions, leaving US CPI as the likeliest trigger.
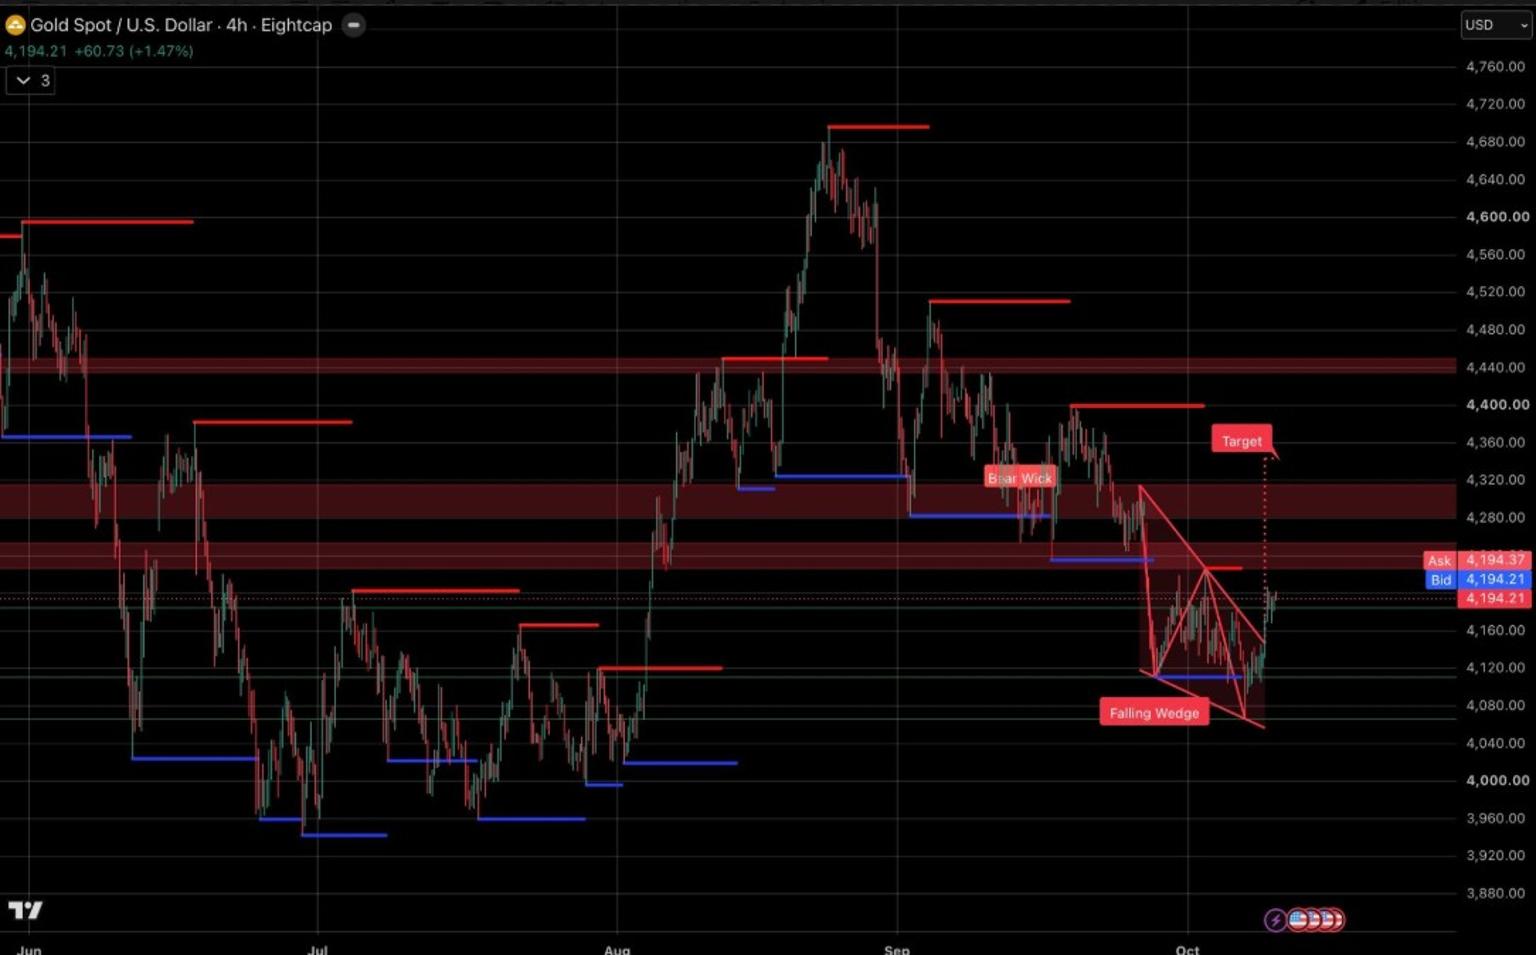
Gold (XAU/USD)
Gold trades at 4,194 after testing 4,070 midweek and then rising 1.4% on Friday as softer US data pulled yields back. Consumer sentiment fell to 46.3 in October from 48.1, while one year inflation expectations rose to 4.7%.
The bigger driver has not changed. The 10 year yield still sits near 5.25%, and a hot CPI would test whether the buyers who returned near 4,130 stay. Mines laid in the Bab el-Mandeb strait add safe-haven support at the margin.
Price Levels
- Support: 4,184 → 4,100 → 4,065
- Resistance: 4,225 → 4,255 → 4,300
Technical View: A falling wedge from late September has broken higher, with a measured target near 4,350. Overhead supply sits between 4,240 and 4,320, where the daily moving averages cluster.
Outlook: Constructive. Buyers are back and Gulf risk is rising, but gold still needs yields to ease before the recovery can clear the supply overhead.
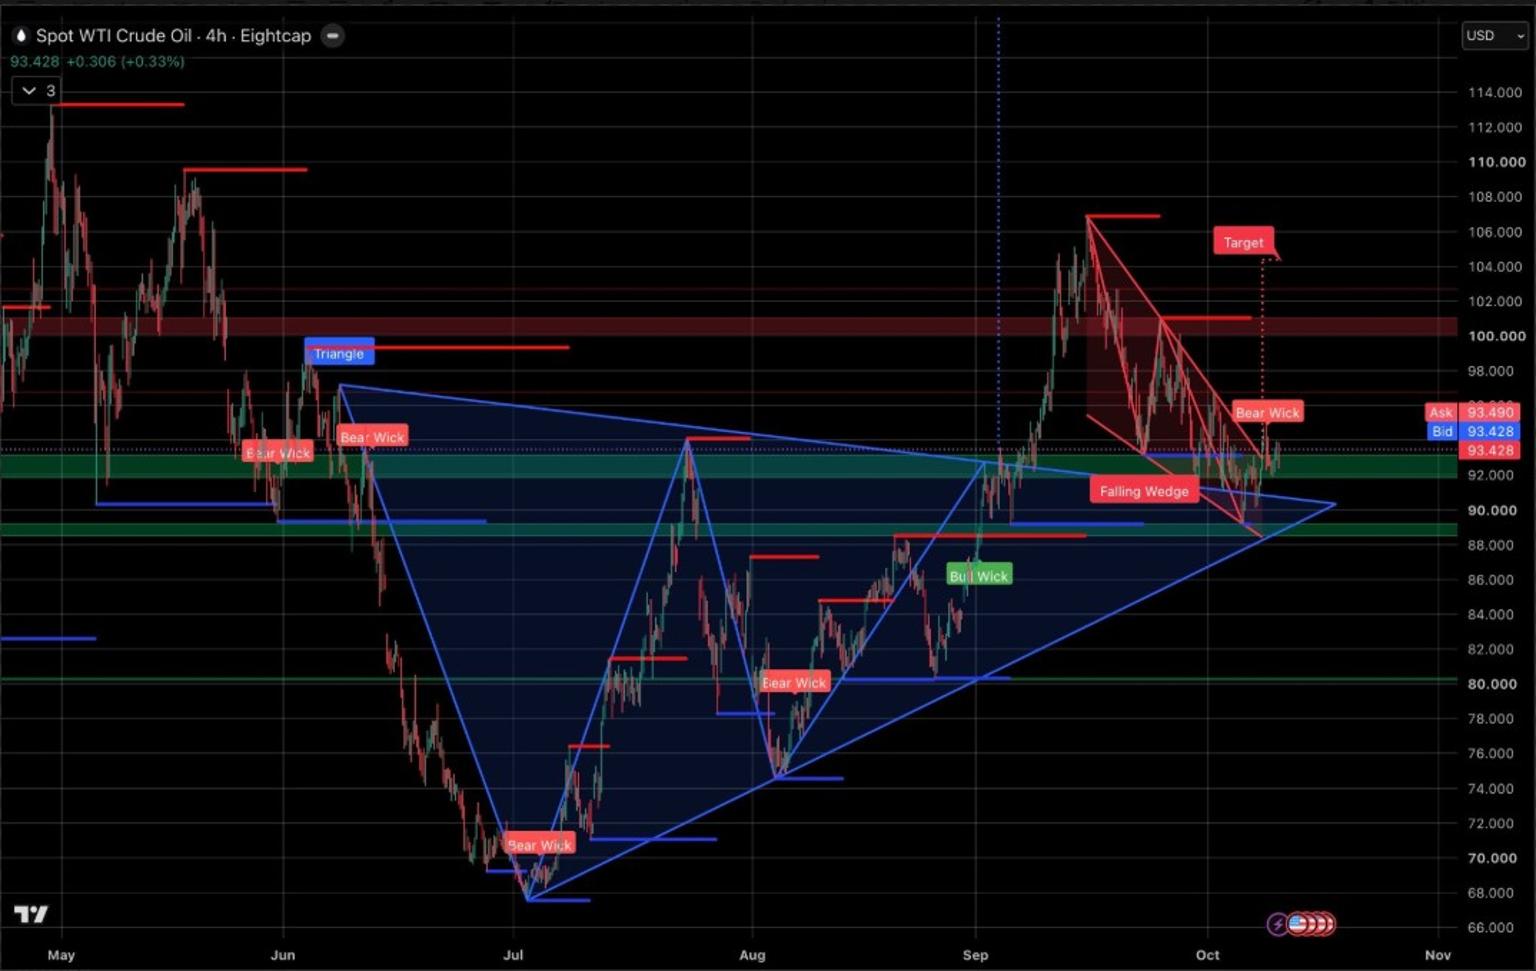
WTI (USO/USD)
WTI trades at 93.48 with two sets of headlines pulling in opposite directions. Houthi strikes on Riyadh’s main airport killed 12 people on Saturday, the fourth attack in a week, and asked whether the US would join strikes, President Trump said: “We may. We’re going to look at it.”
Against that, Washington is adding supply. Treasury licensed Russian diesel imports on Friday, with Trump citing about 13.5 million barrels in coming months, and on Sunday he announced an energy ceasefire between Russia and Ukraine that Kyiv says it supports pending details. Russia supplied about 10% of seaborne diesel before refinery attacks and export bans, though Bloomberg Economics doubts the deal will do much for US fuel prices.
Price Levels
- Support: 91.81 → 89.00 → 80.00
- Resistance: 96.70 → 100.00 → 101.13
Technical View: The falling wedge from the September high near 107 is breaking higher, but a bear wick near 94 shows sellers defending its upper line. The wedge sits near the apex of a larger triangle that began in June.
Outlook: Bullish bias. The risk of a wider Gulf war, with Washington weighing whether to join, outweighs the extra Russian diesel coming to market.
Bitcoin (BTC/USD)
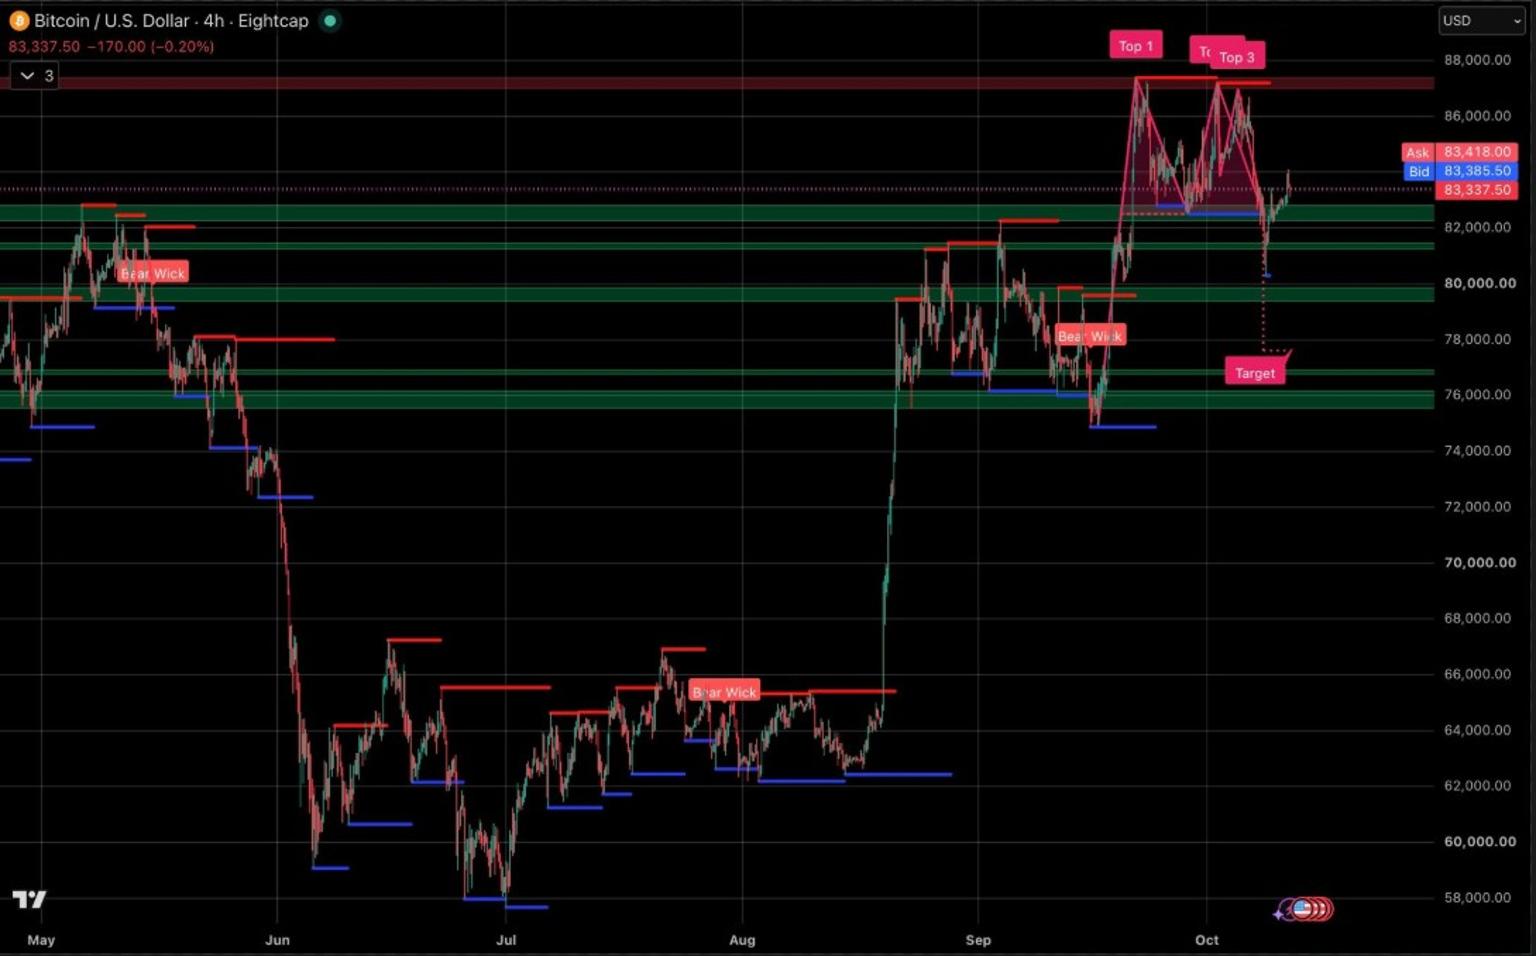
Bitcoin trades at 83,418 after a liquidation-driven drop toward 80,000 last week flushed out leveraged longs. Buyers returned quickly and it has reclaimed the 82,500 area.
The double top we flagged last week has become a triple top at 87,400, and its neckline gave way intraday before buyers stepped back in. CPI matters here through yields: a hot print would test whether last week's buyers hold.
Price Levels
- Support: 82,500 → 81,450 → 79,900
- Resistance: 85,240 → 87,430 → 90,500
Technical View: A triple top at 87,400 caps the range, with the neckline near 82,500 and a measured target around 77,500. Last week's break below the neckline failed to hold.
Outlook: Consolidating. The triple top caps the upside, but last week’s failed breakdown shows buyers still defending the range, so CPI is likely to decide which side gives.
EUR/USD
EUR/USD trades at 1.1187, with the euro down against every G10 currency so far this month as France’s bond turmoil spreads. The French 10 year premium over Germany is the widest since 2012, Italian and Greek spreads have widened with it, and student protests return on Tuesday.
The ECB is focused on inflation rather than rescue, though Lagarde told finance ministers privately that it has tools to stabilise markets if needed, and French bonds rallied on Friday. Bundesbank board member Michael Theurer said there is no systemic sovereign debt crisis but the risks have increased significantly. Lagarde speaks twice on Wednesday, and German inflation lands Tuesday, expected unchanged at 3.3%.
Price Levels
- Support: 1.1170 → 1.1161 → 1.1130
- Resistance: 1.1240 → 1.1277 → 1.1354
Technical View: A double bottom near 1.1160 has formed after the September slide, with a neckline near 1.1275 and a measured target near 1.1390. Price has slipped back toward the lows, so the base is untested rather than confirmed.
Outlook: Bearish. France’s bond stress has become a euro problem, and ECB policymakers see no need yet for emergency tools.
AUD/USD
The Australian dollar trades at 0.6981 after gaining 0.6% last week as the US dollar eased. That bounce has stalled just under 0.6990, where it has now failed twice.
The domestic test comes in two parts: the RBA's minutes on Tuesday, then September jobs on Thursday, expected at 20,000 after 39,500 with unemployment steady at 4.6%. A firm report would revive the case for another hike after markets scaled back November bets.
Price Levels
- Support: 0.6932 → 0.6903 → 0.6864
- Resistance: 0.6990 → 0.7020 → 0.7050
Technical View: The bearish pennant that broke below 0.7000 still carries a measured target near 0.6870. The rebound has formed a double top near 0.6990, just under that broken level.
Outlook: Bearish bias. The bounce has stalled under the old breakdown level, and only a strong jobs report would restore the rate support the Aussie lost last week.
Hang Seng (HK50)
The Hang Seng trades at 24,330, up more than 2% on Monday. China moved to defuse a trade fight with Europe, agreeing a 16-point consensus that includes curbs on hybrid car exports, ahead of an EU leaders' meeting on Thursday that will weigh tougher measures.
Domestic demand remains the weak spot. CPI on Wednesday is expected at 1% from 0.8%, credit demand is sluggish, and the central bank has pushed back on claims the yuan is undervalued as Brussels frames the trade gap as a currency issue.
Price Levels
- Support: 24,240 → 23,740 → 23,190
- Resistance: 24,530 → 24,800 → 25,000
Technical View: A double bottom near 23,700 has formed on the hourly chart, with a measured target near 25,050. Price is now testing the 24,450 to 24,550 band that capped it in late September.
Outlook: Bullish bias. Easing trade tension with Europe and a fresh base on the chart give buyers the edge, provided Thursday's EU summit does not escalate.
USD/CAD
USD/CAD trades at 1.4263 after pushing past the late June high we flagged last week, only to stall at 1.43 on 5 October. It has moved sideways between 1.42 and 1.43 since.
The rate gap is the driver. US policy rates sit around 175 basis points above Canada's, yet Canadian markets still price close to four Bank of Canada hikes by next September, which limits how far that gap can widen. Macklem speaks Wednesday and Friday, and Ottawa's criticism of the US diesel deal with Russia adds another strain to a relationship already under import bans.
Price Levels
- Support: 1.4200 → 1.4150 → 1.4110
- Resistance: 1.4300 → 1.4380 → 1.4410
Technical View: A rectangle between 1.42 and 1.43 has formed at the top of the September rally, with measured targets near 1.4400 above and 1.4110 below. A small triangle inside it is narrowing toward a break.
Outlook: Consolidating. The rate gap still favours the dollar, but momentum has stalled at 1.43 and the pair needs a fresh push from Macklem or US dat
Video transcript
Hello everyone. I’m Alexander Chieffalo from Eightcap, and here is this week’s market update.
Last week, there was big news from tech. Reports that OpenAI’s revenue was well below earlier figures hit semiconductor stocks, and the Nasdaq now sits about 1.5% below its record.
The Fed’s minutes showed full support for September’s hike, but a split on what comes next. Markets price a hold this month, with a December hike still in play.
Gold bounced on softer US data and is trading just under $4,200.
Oil was pulled both ways. Houthi strikes on Saudi Arabia raised supply fears, while Washington cleared Russian diesel imports. WTI is trading around $93.
In Europe, French bond stress has pushed the euro lower against every major currency this month.
Bitcoin is holding around $83,000 after a sharp dip towards $80,000.
This week, Chinese and US inflation data both land on Wednesday. Australia’s jobs report, US producer prices and retail sales follow on Thursday.
Stay sharp, and see you all next week.

Trade the Week Ahead
Explore our AI-powered Economic Calendar to stay ahead of market events.
Alexander Chieffalo | Eightcap Risk Manager
Alexander Chieffalo is Risk Manager at Eightcap.
Related articles
Trade gold CFDs 24/7 with GOLD247
Trade GOLD247, Eightcap's Gold/USD CFD, seven days a week.
17 August 2026
How does forex trading work?
New to forex? Learn how forex trading works in plain English, including currency pairs, price movements, CFDs, leverage and how to practise first.
17 August 2026
The six factors that drive Gold prices
What drives the price of Gold? Gold is considered to be a safe haven asset during periods of market volatility.
27 February 2020


